Story Highlights
- Mark Zuckerberg reached an agreement with Meta’s board to address a proposed California billionaire tax while maintaining majority ownership
- The wealth tax proposal would impose a one-time 5% levy on individuals with net worth exceeding $1 billion, potentially costing Zuckerberg over $11 billion
- The deal allows Zuckerberg to sell non-voting shares to cover tax obligations and includes an eight-year commitment to remain in California
- The arrangement illustrates divergent strategies billionaires are employing to navigate proposed wealth taxation
What Happened
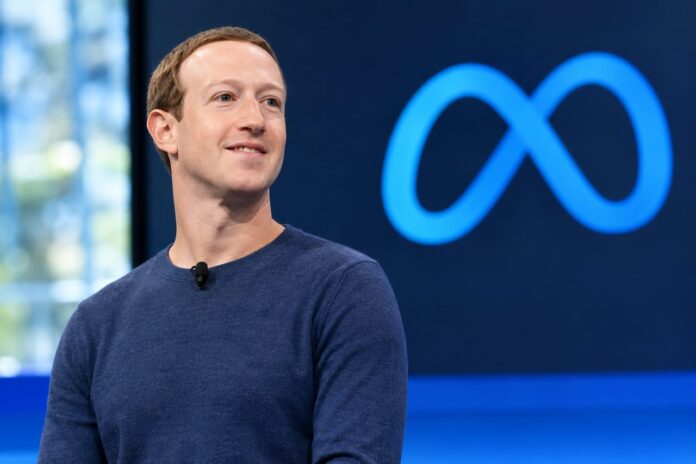
Mark Zuckerberg has negotiated a comprehensive agreement with Meta’s board of directors to manage potential liabilities from California’s proposed billionaire wealth tax while preserving his controlling interest in the technology company. According to regulatory filings released this week, the arrangement provides Zuckerberg with financial flexibility to address tax obligations that could exceed $11 billion if voters approve the measure in the November 3 election.
The California wealth tax proposal would levy a one-time 5% tax on the wealth of state residents whose net worth exceeds $1 billion. As the sixth-richest person globally with an estimated net worth surpassing $220 billion, Zuckerberg would face substantial tax liability should the measure pass. The board agreement authorizes the creation of a new class of non-voting shares that Zuckerberg may sell to generate funds for any purpose, including satisfying potential tax bills.
- Meta announced the shareholder authorization arrangement on Wednesday
- The proposed tax targets approximately a few hundred billionaires currently residing in California
- The tax would apply to individuals with a primary residence in California as of January 1, 2026
- Zuckerberg committed to staying in California for eight years unless unforeseen circumstances arise
Why It Matters
The Zuckerberg arrangement offers significant insights into how ultra-wealthy individuals may prepare for and navigate wealth taxation policies that target investment portfolios rather than earned income. Unlike traditional income taxes, wealth taxes focus on accumulated assets, representing a fundamentally different approach with substantial implications for how billionaires structure their finances and residency decisions.
Supporters of the California wealth tax argue that the Zuckerberg deal validates their position that billionaires will remain in the state rather than flee. Labor union representatives contend that such arrangements demonstrate that even the wealthiest individuals can accommodate wealth taxation without abandoning California. Conversely, opponents, including Democratic Governor Gavin Newsom, have warned that aggressive wealth taxation could incentivize relocation, potentially undermining California’s tax base.
- The agreement preserves Zuckerberg’s majority control while enabling liquidity to cover potential tax obligations
- Proponents view the arrangement as evidence that wealth taxes will not cause mass billionaire exodus from California
- Opponents remain concerned that wealth taxes could reduce the state’s tax base and affect public services
- The deal illustrates complex financial strategies available to ultra-wealthy individuals facing new taxation
Political and Public Context
California’s proposed wealth tax exists within a broader national debate over tax fairness and the appropriate level of taxation on accumulated wealth. The measure has attracted support from Vermont Senator Bernie Sanders and labor organizations such as SEIU United Healthcare Workers West. Revenue from the wealth tax is designated for specific purposes, with the majority allocated to backfill federal healthcare funding cuts, while 10% would support education and food assistance initiatives.
Other technology industry figures have adopted markedly different approaches to the wealth tax proposal. Google co-founders Sergey Brin and Larry Page have begun reducing their ties to California, while technology entrepreneurs and venture capitalists have mobilized significant political opposition through the committee Building a Better California. This political committee has raised more than $333 million in opposition funding, reflecting the substantial financial resources deployed by billionaire-backed groups.
- Supporters of the tax proposal include Senator Bernie Sanders and SEIU United Healthcare Workers West
- Governor Gavin Newsom opposes the measure, citing concerns about billionaire flight and state revenue losses
- The opposition committee Building a Better California has raised over $333 million
- Google co-founders Sergey Brin and Larry Page represent the billionaire flight model that opponents warn about
Meta’s non-voting share plan could help Mark Zuckerberg cover a potential California wealth-tax bill without losing voting control. In return, he’ll stay in-state for eight years—a striking corporate trade-off.
https://t.co/LIyAlrijGX— Azat TV (@azattelevision) October 23, 2026
What Happens Next
The California wealth tax proposal remains subject to voter approval in the November 3 election. The outcome will determine whether the one-time 5% tax on billionaire wealth becomes law and triggers actual tax obligations for affected individuals like Zuckerberg. If approved, the tax would take effect for residents with primary California residences as of January 1, 2026.
Zuckerberg’s board agreement establishes a framework for managing tax liability should voters approve the measure. The political campaign leading to the November election will likely see continued mobilization by both supporters and opponents of the wealth tax, with the Zuckerberg deal potentially serving as a focal point in broader discussions about whether wealth taxation policies would effectively retain billionaires in California.
- California voters will decide the wealth tax proposal’s fate in the November 3 election
- If approved, the tax would apply to residents with primary California residences beginning January 1, 2026
- Ongoing political campaigns will likely reference the Zuckerberg arrangement as evidence supporting competing positions
- Implementation of the tax would require regulatory guidance on valuation and compliance procedures